ai-hedge-fund: The Open-Source Repo That Turns an LLM Swarm Into an Investment Committee
A look inside the architecture that separates market storytelling, hard valuation math, and risk control into one workflow that behaves more like a hedge fund than a chatbot.
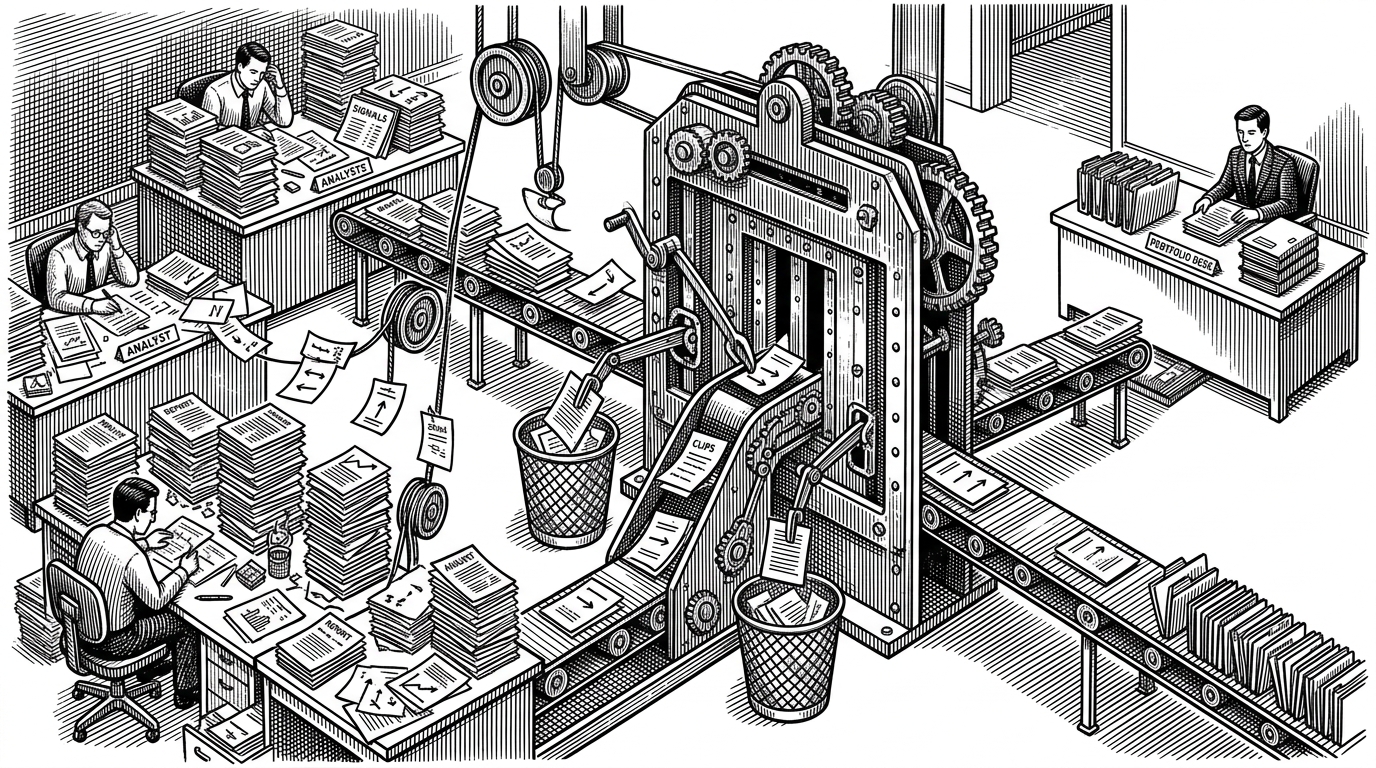
- `ai-hedge-fund` is interesting because it treats coordination as the core product, not the LLM prompt.
- The repo boxes in narrative agents with deterministic valuation and risk logic, so language never gets the final word by itself.
- Risk management matters more than the chat because it shrinks position authority when volatility or correlation rises.
- The project is best understood as an LLM-native committee system, not as a generic trading bot or a backtester with extra gloss.
The easiest mistake is to call this an AI stock picker. That misses the point. `ai-hedge-fund` is a digital investment committee, where model outputs are only one input to a workflow that also includes valuation math, volatility controls, correlation checks, and portfolio sizing.
That is why the repo stands out. Most AI trading projects either stop at chat, or bolt AI onto a conventional quant stack. This one does something more deliberate: it gives each agent a narrow job, then forces the system to reconcile those jobs before a position can exist.
The boardroom is the product
The central idea is simple. A hedge fund is not one genius. It is a process with specialists, frictions, and checks. This repo mirrors that reality with a workflow that looks less like a chatbot and more like a committee meeting where every voice has a role, but not every voice gets a vote.
That framing matters because it explains the project’s real novelty. The agent swarm is not the headline. The handoff between agents is. The system is designed so that narrative, math, and risk do not blur into one blob of reasoning.
From one model to many roles
The architecture fans out from market data into specialist agents, then fans back in through a shared state. In the repository, this orchestration lives in the LangGraph workflow in `src/main.py`, with shared memory in the graph state and agent modules split by responsibility.
# Conceptual shape of the workflow
market_data -> [valuation_agent, sentiment_agent, technical_agent]
[valuation_agent, sentiment_agent, technical_agent] -> shared_state
shared_state -> risk_manager
risk_manager -> portfolio_manager
portfolio_manager -> final_signal
That pattern is the opposite of a monolithic reasoning loop. Each analyst can contribute in parallel, but the system only becomes actionable after the shared evidence is filtered through risk and portfolio logic. In other words, the repo is not trying to make one model smarter. It is trying to make the decision path more credible.
Why the risk agent matters more than the chat
The risk manager is the credibility anchor. According to the codebase research, it pulls historical prices, computes annualized volatility, and builds correlation matrices before it approves or shrinks a position. That means authority is conditional. If the market is noisy or the asset is too similar to existing holdings, the trade gets smaller.
That is a meaningful design choice. LLMs can describe a thesis. They cannot, by themselves, enforce exposure discipline. The repo makes risk a first-class gate, not a postscript.
The goal of this project is not to create a money-printing machine, but to explore the intersection of AI and finance.
That quote captures the project well. It is a research-y system, not a promise of alpha. The interesting part is how seriously it treats the mechanics around the model output.
Valuation is not vibes
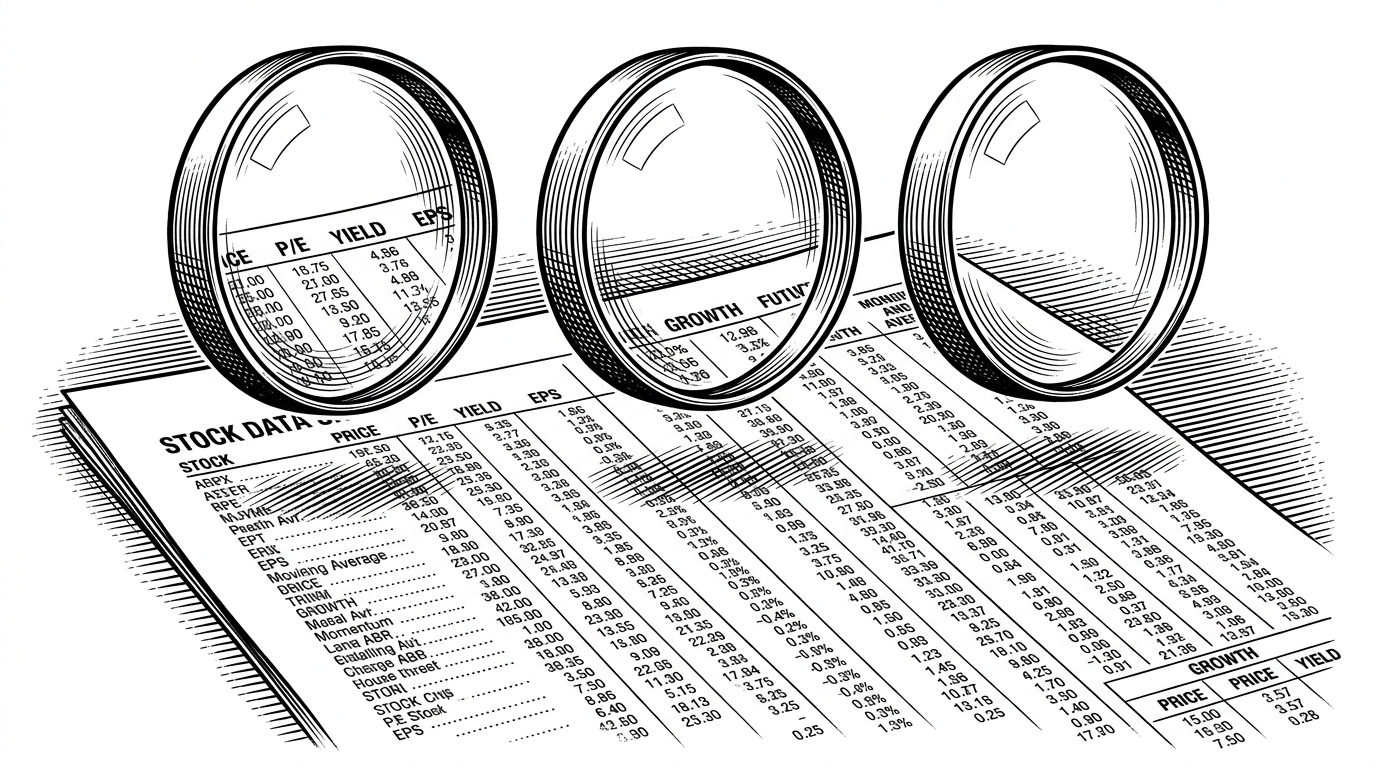
The valuation layer is where the project stops pretending that language can substitute for finance. The repository research points to owner earnings, DCF, and EV/EBITDA as part of the valuation logic. That matters because the model is not asked to invent intrinsic value from prose. It is asked to interpret real financial inputs through hard formulas.
# The point is not the exact formula here.
# The point is that intrinsic value comes from finance math,
# while the LLM helps frame and explain the result.

intrinsic_value = weighted_average([
    owner_earnings_value,
    discounted_cash_flow_value,
    ev_ebitda_value,
])
That separation is the project’s best instinct. The LLM handles judgment, framing, and comparison. The deterministic code handles arithmetic and thresholds. If you want a system that feels more like an institution than a demo, that split is the right one.
The most surprising trick: persona as a filter
This is where the repo gets genuinely interesting. The personas do not inject new facts. They reinterpret the same facts through different investor philosophies. Buffett, Taleb, Graham, and others become prompt-level lenses that shape how the committee reads the same evidence.
That makes the persona layer a filter, not a source. It is a clever design because it preserves a single factual substrate while allowing multiple decision styles to compete over it. The data stays fixed. The interpretation changes.
How it stacks up against classic quant frameworks
| Project | Primary goal | Core intelligence | Workflow style | Best fit |
|---|---|---|---|---|
| ai-hedge-fund | LLM-native investment committee | Multi-agent prompts plus deterministic finance logic | Fan-out, fan-in decision pipeline | Builders exploring hybrid AI decision systems |
| Lean | Production algorithmic trading | Rules, data, and strategy code | Backtest and live-trading engine | Serious quant teams |
| Zipline | Historical strategy research | Python strategy scripts | Backtesting framework | Researchers and educators |
| Backtrader | Flexible Python trading | Strategy code and broker integrations | Single-strategy simulation and execution | Independent traders |
| FinRL | Reinforcement learning finance | DRL agents | Train, evaluate, optimize | ML researchers focused on RL |
The comparison is clean. Lean, Zipline, Backtrader, and FinRL are built around trading infrastructure or learning loops. `ai-hedge-fund` is built around a governance pattern. Its core question is not only, “What should we buy?” It is, “How should a committee arrive at a defensible answer?”
What this repo really is
It is not production hedge fund software. It is a proof-of-concept for hybrid intelligence: language models for interpretation, formulas for valuation, and workflow design for control. That combination is what makes the project worth studying.
The larger lesson reaches beyond finance. Any multi-agent system that matters will need the same three layers: narrative, constraint, and orchestration. `ai-hedge-fund` shows one very legible way to wire them together.