QuantConnect LEAN: The Trading Engine Built to Stop You Fooling Yourself
A deep look at the `Slice` abstraction, the C# core, and the cross-language design that makes LEAN feel Pythonic without sacrificing performance or backtest integrity.
- LEAN’s defining idea is not speed, but time discipline, because it turns asynchronous market inputs into one synchronized decision surface.
- The `Slice` abstraction is the engine’s anti-look-ahead mechanism, since strategy code sees only what is valid at the current moment.
- C# owns determinism and throughput while Python owns strategy ergonomics, which lets LEAN feel friendly without moving the core out of process.
- Regression data and live brokerage integrations make correctness part of the product, not a separate testing exercise.
The Engine Does Not See a Stream. It Sees a Slice.
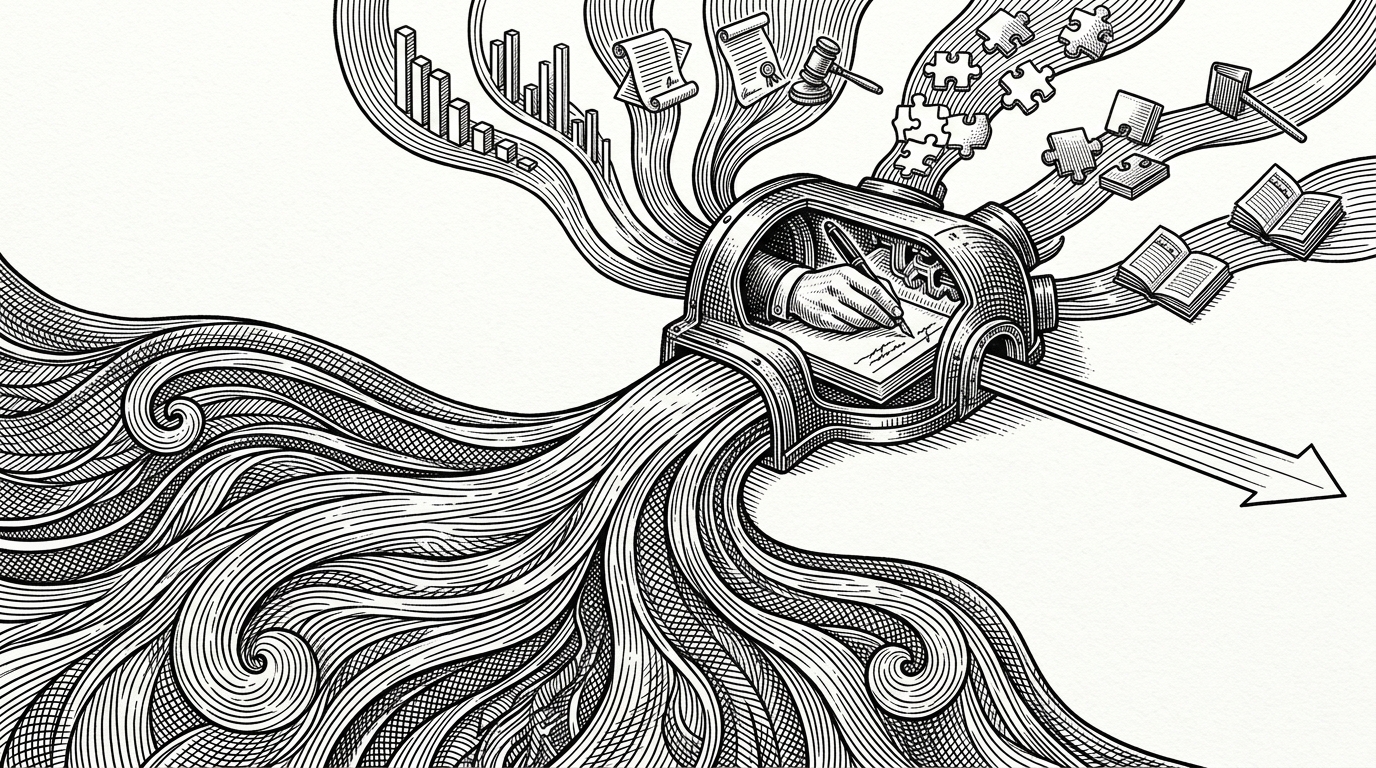
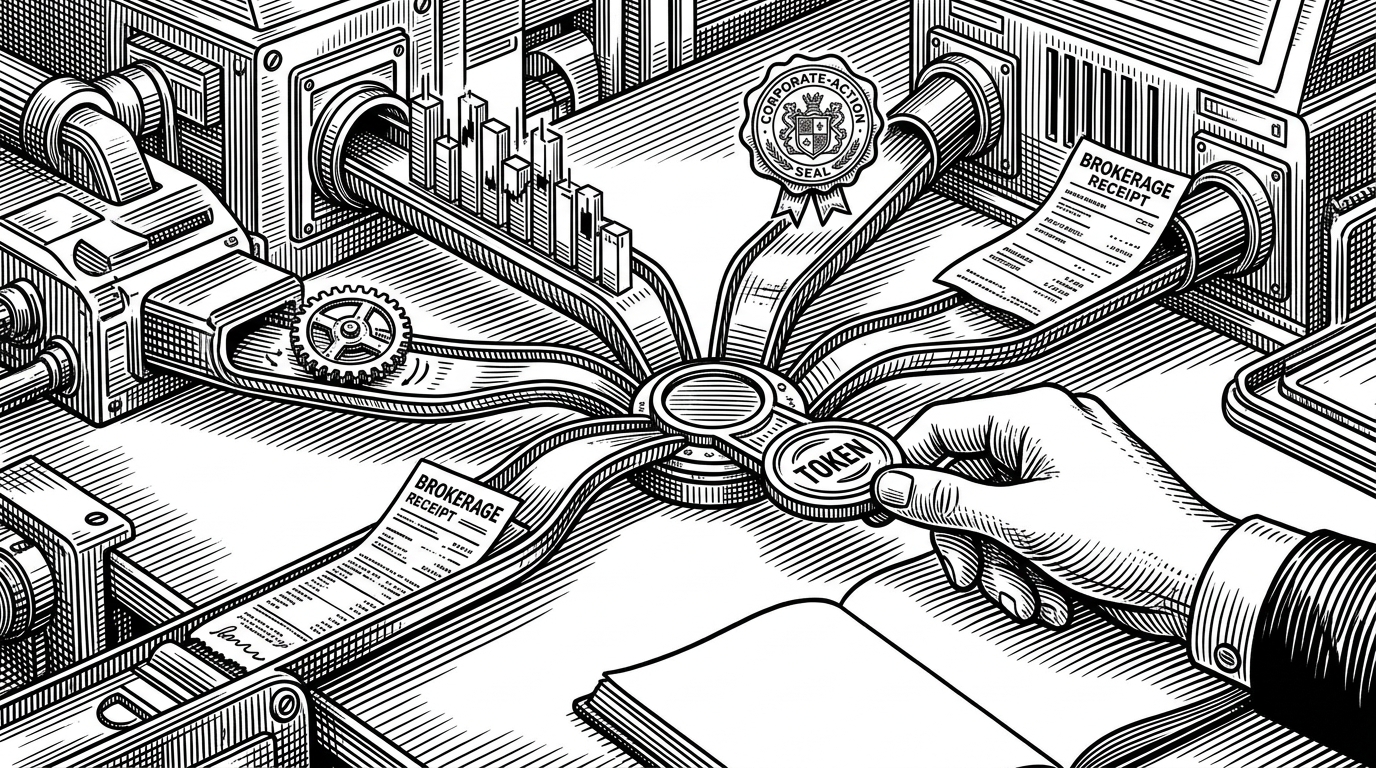
LEAN’s most important abstraction is also its quietest one: `Slice`. Instead of handing your strategy a raw firehose of market updates, the engine gathers everything that is valid at a given moment into a single time-aligned packet. That includes bars, ticks, splits, dividends, universe changes, and brokerage events.
That design sounds simple until you try to build it. Markets do not arrive in neat sync, and a strategy that reads data one feed at a time can accidentally peek into the future. LEAN’s answer is to make the engine assemble the moment before the algorithm sees it.
Why That Matters More Than Speed
A trading engine can be fast and still be wrong. If it misaligns symbols, mishandles resolutions, or lets a decision see information that was not available at that time, the backtest becomes fiction. The bug is not just in performance, it is in time.
| Problem | Naive engine | LEAN |
|---|---|---|
| Multi-asset timing | Each feed is handled as it arrives, which makes cross-symbol decisions fragile. | Feeds are synchronized into one `Slice` before strategy logic runs. |
| Look-ahead bias | Future data can leak through ordering or buffering mistakes. | Only data valid at engine time is exposed to `OnData`. |
| Backtest to live parity | Research code and live code often diverge in subtle ways. | The same event-driven model powers both modes. |
| Debugging | Errors hide in latency, ordering, and partial updates. | The callback boundary makes timing behavior explicit. |
This is why event-driven design matters more than raw throughput in this domain. A correct answer that arrives later is useful. A fast answer that cheats is useless.
public class BasicTemplateAlgorithm : QCAlgorithm
{
    public override void Initialize()
    {
        SetCash(100000);
        AddEquity("SPY", Resolution.Minute);
    }

    public override void OnData(Slice slice)
    {
        if (!slice.Bars.ContainsKey("SPY")) return;

        var bar = slice.Bars["SPY"];
        if (bar.Close > bar.Open)
        {
            SetHoldings("SPY", 1.0m);
        }
    }
}
C# Owns the Clock, Python Owns the Strategy
LEAN’s polyglot design is a practical compromise. The engine core stays in C# because deterministic event processing, tight memory control, and high-throughput data handling matter more there than developer convenience. Python sits on top for strategy authoring through PythonNet, which means the user experience stays familiar without pushing the whole system through a slow IPC boundary.
| Layer | C# core | Python layer |
|---|---|---|
| Job | Runs the event loop, data plumbing, brokerage integration, and timing rules. | Defines strategies, research logic, and high-level business rules. |
| Strength | Performance, determinism, type safety. | Familiar syntax, scientific libraries, quick iteration. |
| Trade-off | Harder to extend casually. | Slower than native C#, but kept close to the engine. |
| Design goal | Own the clock. | Own the idea. |
LEAN is a powerful, open-source algorithmic trading engine built for easy strategy research, backtesting, and live trading. We designed it to be modular and extensible, allowing developers to plug in their own data sources, brokerages, and transaction models.
That modularity is not just a product pitch. It is visible in the codebase structure, the launch tooling, and the way the engine keeps core execution separate from strategy templates. The result is a Pythonic face on top of a C# machine.
The Template File That Tells You Everything
If you want the shortest route into LEAN, start with `BasicTemplateAlgorithm.cs`. It shows the lifecycle plainly: `Initialize()` sets the universe and brokerage context, then `OnData(Slice slice)` becomes the recurring decision point. That single callback is the contract that makes the rest of the engine legible.
The file also reveals something more unusual: regression metadata. Strategy examples are not just examples. They are executable expectations with historical performance attached, which turns the template into a benchmark for the engine itself.
public override void Initialize()
{
    SetStartDate(2013, 10, 7);
    SetEndDate(2013, 11, 8);
    SetCash(100000);
    AddEquity("SPY");
}

public override void OnData(Slice slice)
{
    // Strategy logic runs here on synchronized market data
}

// Regression metadata in strategy files helps validate behavior
// against expected statistics after engine changes.
Regression Tests Are Part of the Product
Most frameworks treat correctness as an external discipline. LEAN folds it into the repository. The presence of regression algorithms and expected statistics makes the engine continuously check whether a code change altered the meaning of a trade path.
That matters because trading code is only useful if it remains stable under change. If a dependency upgrade or execution tweak changes fills, order timing, or portfolio outcomes, LEAN is built to catch it before the user trusts the result.
- Regression files encode expected outcomes alongside strategy logic.
- Test failures can surface changes in execution semantics, not just code crashes.
- That makes backtesting a control system, not a one-off experiment.
From Local Research to Live Trading
LEAN’s deployment story is one of its strongest strategic choices. It does not force you into a notebook toy or a hosted black box. You can work locally, often through Docker and the LEAN CLI, or move the same strategy into QuantConnect’s cloud and brokerage integrations.
That continuity matters because research environments are easy to fake and hard to trust. LEAN reduces the gap between what you tested and what you traded by keeping the engine model stable across local and live workflows.
| Platform | Backtest depth | Live trading | Language model | Best fit |
|---|---|---|---|---|
| Zipline | Strong for Python backtests | Limited or community-driven | Python | Researchers who want a pure Python lineage |
| Backtrader | Flexible and approachable | Supported through integrations | Python | Solo developers who want maximum scriptability |
| IBKR API | No framework layer | Direct broker access | Language-agnostic | Builders who want raw control |
| TradingView Pine Script | Lightweight chart-based testing | Alerts and broker links | Pine Script | Visual traders and quick prototypes |
| LEAN | Institutional-style event engine | Native path through broker models | C# core with Python strategy layer | Teams that want research-to-live continuity |
LEAN wins when the question is not just whether a strategy works, but whether the same strategy can survive the trip from research to execution without changing shape.
The goal of LEAN is to provide a level playing field for quant traders. By open-sourcing the core engine, we allow anyone to backtest and deploy institutional-grade strategies without the massive upfront infrastructure costs.
What LEAN Wins, and What It Does Not Try to Be
LEAN is not the lightest option. It is not the quickest path to a first chart, either. What it tries to be is more specific: a standardized, professional-grade trading engine that keeps timing, execution, and portability in one coherent system.
That puts it in a narrow but valuable niche. Compared with simpler tools, LEAN asks for more setup. In return, it gives you a stronger guarantee that your backtest is describing the same world your live strategy will enter.
For serious systematic trading, that bargain makes sense. The point is not that LEAN is fashionable. The point is that it is disciplined.